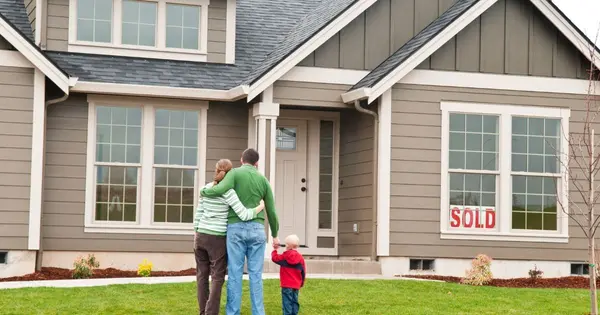
Maybe not.
If you already own a home and have been thinking about buying another one, you may have assumed that you need to sell your current home before you can qualify for your next mortgage.
But a recent update to Fannie Mae's rental income guidelines could make it easier for some homeowners to keep their current home as a rental while purchasing their next home.
My lender recently brought this update to my attention, and I wanted to share it because it could be an important option for homeowners who are ready to make a move but aren't sure what to do with the home they already own.
Here's what you should know.
What Changed?
Fannie Mae updated its guidelines on September 2, 2026, regarding rental income from a home that a homeowner is leaving and converting into a rental property. Lenders must implement these changes by November 1, 2026, although some lenders may begin using the updated guidelines sooner.
One of the important changes is that homeowners may not need to already have a signed lease in place for the rental income from their current home to be considered.
Instead, the potential rental income can be determined using acceptable documentation, which may include an appraisal or rental market analysis. Certain rental market analysis tools, including Zillow or Redfin, may also be used with at least three comparable rental properties.
In simple terms, this could give some homeowners another option when they're ready to purchase their next home.
How Could the Rental Income Help?
Under the updated guidelines, 75% of the property's market rent can be used when calculating rental income for qualifying purposes.
The goal is to help offset the housing expense associated with the home you're planning to turn into a rental.
For homeowners with limited rental property management experience, the rental income is generally used to help offset the payment on the home being converted into a rental rather than simply being treated as additional income.
Your lender will look at the property's rental value, your current housing payment, your experience managing rental properties, and the rest of your financial picture to determine how the income can be used for your specific loan.
What If You've Never Been a Landlord Before?
There is one thing to keep in mind if you've never been a landlord before.
You may need to have six months of reserves for the home you're leaving.
Here's an easy example:
Let's say you're currently paying $1,000 a month for the home you live in.
You decide to move into a new home and keep your current home as a rental.
If you don't have previous property management experience, you may need to have $6,000 set aside in the bank.
That's simply six months of your $1,000 monthly payment:
$1,000 × 6 months = $6,000
And that $6,000 would need to be available after you've covered your down payment and the other funds needed to purchase your new home.
So, in simple terms, you're not necessarily being asked to spend an extra $6,000. You need to show that you still have those funds available as a financial cushion after you've paid for the other costs associated with buying your next home.
As my lender explained to me, this usually isn't a major issue unless someone is already having a difficult time coming up with the cash needed for their new purchase.
Your actual requirements can vary depending on your loan and financial situation, so this is something your lender can help you determine.
Do You Need a Signed Lease?
Not necessarily.
This is one of the changes my lender specifically brought to my attention.
For this type of situation, Fannie Mae's updated guidelines allow the rental income to be supported through other acceptable documentation instead of requiring an existing lease.
That can include an appraisal or rental market analysis. In certain situations, three comparable rental properties from sources such as Zillow or Redfin can be used to help determine the property's market rent.
This could make the process more flexible for homeowners who are planning to move out of their current home and turn it into a rental.
What About Rental Income Above the Mortgage Payment?
One thing that's important to understand is that this isn't necessarily a situation where you simply take the rent you could collect and count all of it as additional income.
For borrowers with limited rental property management experience, the rental income may be used to offset the housing expense of the property rather than simply becoming extra qualifying income.
If you have more experience managing rental properties, different rules may apply to how positive rental income can be used.
Your lender will review your specific circumstances and determine how the rental income can be treated for your loan.
What Does This Mean for Utah Homeowners?
The biggest takeaway is simple:
You may not automatically have to sell your current home before buying your next one.
If your current home could make sense as a rental, there may be a way to keep it while purchasing another property.
Of course, keeping your current home as a rental isn't the right decision for everyone. You'll want to consider things like:
• Your current mortgage payment
• Potential rental income
• Property taxes and insurance
• HOA costs, if applicable
• Maintenance and repairs
• Vacancy
• Required reserves
• Your overall financial goals
Your lender can help you understand the financing side, while your Realtor can help you evaluate the real estate side of the decision.
Before You Decide to Sell, Let's Talk
If you've been thinking:
"I want to buy another home, but I don't think I can qualify unless I sell my current one."
Don't make that assumption before talking with a lender.
There may be an option to keep your current home as a rental and purchase your next home, depending on your financial situation, the property, and your loan requirements.
If you're a Utah homeowner considering your next move, reach out to me before you decide what to do with your current home.
I work with a lender who can review your situation, explain how these guidelines may apply to you, and help you understand what options may be available.
From there, my team and I can help you navigate the purchase of your next home and determine what makes the most sense for your goals.
Ready to See What's Possible?
📞 Call or text me today, and let's make a plan.
You may have more options than you think. 🏡
Important InformationThis article is for educational purposes only and is not a guarantee of loan approval or eligibility. Fannie Mae guidelines, lender requirements, and individual loan circumstances can affect how rental income is calculated, what reserves may be required, and whether rental income can be used for qualification.
The examples in this article are for illustration purposes and are based on information shared with me by a Utah lending professional. Your actual requirements may be different.
Before making a decision about keeping your current home as a rental or purchasing another property, speak with a qualified lender about your specific financial and loan situation.
FROM OUR BLOG
2026 Utah Farmers Market Guide: Salt Lake, Utah, Tooele & Davis Counties
There’s something special about visiting a farmers' market on a warm Utah morning or evening. From fresh fruits and vegetables to baked goods, locally made products, food vendors, and handmade goods, farmers' markets are a wonderful way to shop local and experience the communities around us. If you'

Utah Ranks #2 for Independence: What It Means for Buyers, Sellers, and Investors
Utah Ranks #2 for Independence: What It Means for Buyers, Sellers, and Investors When you think of independence, images of wide-open spaces, self-reliant pioneers, and communities that thrive on their own terms might come to mind. According to a recent WalletHub study, Utah embodies these ideals mor
What 125 New Jobs in Draper Could Mean for Utah’s Real Estate Market
Draper is once again making headlines as a magnet for both businesses and new residents in Utah. The latest buzz? Rincon Research Corp., a respected engineering and technology firm from Arizona, is setting up a 37,000-square-foot office in Draper. This expansion is expected to create about 125 new j
Found This Useful?
Contact me
Hi, I’m Daisy Hernandez, a Utah Realtor® dedicated to helping people feel confident and informed throughout their real estate journey.
With several years of experience in real estate, I’ve learned that buying or selling a home is about so much more than a transaction. It’s about people, goals, and creating the next chapter of your life. My goal is to make the process feel less overwhelming and more empowering by being someone you can trust, communicate openly with, and rely on every step of the way.
I’m passionate about helping first-time homebuyers, sellers, families, and anyone looking to make a move here in Utah. With experience working with both buyers and sellers, I understand the unique needs that come with every real estate transaction. Whether you’re searching for the right home or preparing to sell one, I’m committed to providing knowledgeable guidance, strong communication, and personalized service from start to finish. I also understand how important it is to have an agent who truly listens to your needs and goals rather than simply focusing on making a sale.
As a bilingual Realtor®, I’m proud to offer service in both English and Spanish, making real estate more accessible for the people and families I have the privilege of working with.
Whether you’re ready to buy your first home, sell your current one, invest in real estate, or simply have questions about where to start, I’m here to help you navigate the process with honesty, patience, and dedication.
Your goals are important to me, and I’d be honored to help you turn them into a reality.